Insurance claims
Roof insurance claim help and insurance roof replacement
A roof insurance claim is easier when you know who does what. We document the damage, you file and talk with your insurer, and the adjuster decides what your policy covers.
Mobley Brothers Roofing & Renovation has helped homeowners across East and Middle Tennessee with storm damage and insurance roof replacement since 2007. We are roofers, not adjusters or lawyers, and we will never promise that a claim will be approved. What we can promise is a careful inspection, clear photos, a written estimate and honest answers about whether your damage is even worth a claim.
This page explains how a roof insurance claim usually works, what the roofer can and cannot do, and how our Knoxville and Lebanon offices help you keep the facts about your roof straight from the first inspection to the final photo of the finished work.
How a roof insurance claim usually works
- 01
Find out what happened to the roof
Before you call your insurer, it helps to know whether the roof is actually damaged. We inspect it, take photos and tell you what we see. Sometimes the answer is that the roof came through fine, and you have saved yourself a claim.
- 02
You file the claim
The policyholder has to make the claim. You contact your insurance company, online or by phone, and they assign an adjuster.
- 03
The adjuster inspects
The adjuster visits and looks at the roof for the insurance company. You can share our photos and estimate, and if you want us there, we can meet the adjuster on site to point out what we documented.
- 04
The insurer decides
The insurance company decides what the policy covers and sends its paperwork. That decision is theirs alone. Once you have it, we go over it with you and schedule any repair or insurance roof replacement you choose to have us do.
- 05
We do the work and document it
We complete the work, then provide photos and documentation of the finished repair or replacement, which insurers may ask for as part of reimbursement.
Signs of damage worth a claim conversation
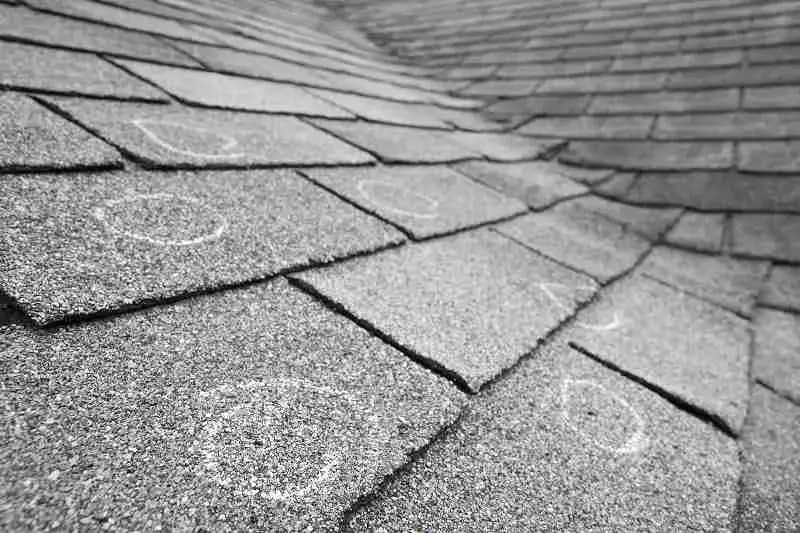
Not all storm damage shows the day after. Lifted seals, shingles bruised by hail and loosened flashing can take weeks or months to turn into a leak, so an inspection is worth asking for even when the roof looked fine from the driveway.
Not every problem is a claim. Insurance policies are generally written for sudden damage, such as a storm, not for a roof wearing out with age. These are the signs that usually justify a closer look after a storm.
- Shingles, ridge caps or pieces of flashing on the ground
- Small round dents in gutters, downspouts or metal vents after hail
- Heavy granule loss washing out of the downspouts
- New stains on ceilings or damp insulation in the attic
- A tree or large limb that struck the roof
- Neighbors on your street having roofs inspected after the same storm
Who does what: homeowner, adjuster and roofer
Most of the frustration in a roof insurance claim comes from not knowing whose job something is. This is how the roles usually divide.
| Who | What they do | What they do not do |
|---|---|---|
| Homeowner | Files the claim, talks with the insurer, reviews the policy, pays the deductible, chooses the contractor | Does not need to climb on the roof or prove damage alone |
| Insurance adjuster | Inspects for the insurance company and reports what the policy covers | Does not work for the homeowner or the roofer |
| Mobley Brothers | Inspects, photographs, writes estimates, can meet the adjuster on site, supplies documentation, does the work | Does not file the claim, negotiate with the insurer, represent the homeowner, or promise approval |
Our role in a repair or insurance roof replacement
When you call us after a storm, a repairman walks the roof and the attic when needed, and photographs every finding. Our team includes a HAAG Certified Inspector for residential roofs, a forensic certification built for documenting damage clearly enough to discuss with insurance adjusters. You get the photos and an electronic written proposal that shows what we would repair or replace.
If the adjuster wants to see what we saw, we can meet them at the house. We share our observations and point out damage, but the conversation about money is between you and your insurance company. We are not allowed to negotiate your claim or represent you to the insurer, and we would rather tell you that plainly than let you believe otherwise.
Sometimes an insurance company asks a homeowner about the condition of a roof for other reasons, such as a policy review. After an inspection, we can write up what we found, or provide a letter documenting repair work we performed, so you have something in writing to send them.
When the insurer approves an insurance roof replacement and you choose us to do it, the job runs like any other replacement. We protect the property, with the Catch-All system where required, work to the manufacturer's standards as a GAF Master Elite residential contractor, and send photos of the finished roof for your records.
Shingle matching and forensic documentation
Tennessee treats matching as part of a fair settlement. In 2017 the state's Commissioner of Commerce and Insurance confirmed that when replaced materials cannot be made to match the rest of the roof in color, quality or size, the insurer should replace enough to give the roof a reasonably uniform appearance under the policy's terms. That is why the shingle sample report matters: if the lab says no current shingle matches, the report supports replacing more than the damaged slope. We give you the documentation; how the policy applies is a conversation between you and your insurer.
Matching is one of the hardest parts of a roof insurance claim. A shingle line can still be in production and no longer come in the same color, so a repair would leave a patch that does not match the rest of the roof. In that situation, we can send samples of your old shingles out for testing. The report that comes back says whether a new shingle will match or not, and it is a fact you can present to your insurance company.
Here is an honest example of what documentation can and cannot do. A homeowner had a lightning strike that blew out soffit and knocked out roof vents. The insurer's first answer was to cover only what was visibly broken. We sent out samples and checked the shingles and the siding, and the insurer approved the upper roof. The front porch and garage, at a lower elevation, were not covered, and the homeowner paid for those. Good documentation made the facts clear. It did not guarantee everything would be covered, and it never does.
If the insurer's decision does not match what we found
Adjusters are people, and sometimes they miss things or see them differently. If your claim is denied or comes back smaller than the damage we documented, start by asking your insurance company to explain the decision in writing and what information would help them review it. We can provide our photos, our estimate and any test reports again.
Some homeowners choose to hire a licensed public adjuster, who can represent a policyholder in a way a roofer cannot. The Tennessee Department of Commerce and Insurance lets you verify an insurance license and file a complaint if you believe an insurer handled your claim unfairly. Its Homeowners Insurance 101 guide is a good plain-language primer before you file anything.
Records that help with any future roof insurance claim
After a storm we also put the date and type of weather event in your file, the documented proof of storm history that adjusters ask for, next to the photos and the written estimate.
Insurers look at the condition of a roof before the storm as well as after it. A record of inspections and repairs makes it much easier to show that damage is new. Keep the photos and proposals we send you, keep receipts for any roof work, and have the roof looked at after major storms even when nothing seems wrong.
We also recommend clearing debris from valleys, gutters and around pipe boots in the fall. Leaves that rot in those spots cause leaks that no policy is written to cover, and a maintained roof is a stronger roof when the next storm comes.
Worth knowing
Start your roof insurance claim with an honest inspection
Before you file a roof insurance claim, let us look at the roof and show you what we find. Call our Lebanon office at (615) 455-3131 for Middle Tennessee or our Knoxville office at (865) 205-0800 for East Tennessee. The team offers free roof inspections, and if you end up with an insurance roof replacement, we will be there from the first photo to the last.
Request a free estimate
A few details help us send the right person. If water is coming in right now, call instead.
Google reviews
What customers say
Lebanon 4.9 stars from 94 · Knoxville 4.9 stars from 286 reviews
“Mike was with us every step of the way, even going so far as to join in on calls with the insurance company. This was a months long process during which time the Mobley Bros team effected temporary repairs to keep the rain out.”
“I contacted Mike after our insurance adjuster said we needed a full roof replacement due to wind and hail damage following a big storm. Mobley Brothers roofing was recommended to us when I asked my local State Farm agent for a reputable roofer, and I'm glad we followed their recommendation! Mike was very professional and transparent through the entire process, and we couldn't be happier with the finished product.”
“They were able to provide us with a letter for the insurance company documenting the work they had performed. Laura called later to make sure that I had everything I needed to support my mother. I found them to be very helpful and also very professional.”
Certifications and accreditations
All 15 credentials and programsFAQ
Questions homeowners ask
Straight answers, the way we would give them on your driveway. If yours is not here, call the office and ask.
More questions we get askedShould I call my insurance company or a roofer first?
It usually helps to have a roofer look first. An inspection tells you whether there is real storm damage and how much, which helps you decide whether a claim makes sense at all. If we find nothing, you have avoided an unnecessary claim. If we find damage, you file with our photos and estimate in hand. Your policy may have its own reporting rules, so check it or ask your agent.
Can Mobley Brothers file or negotiate my claim for me?
No. The policyholder files the claim, and we are not allowed to negotiate with your insurance company or represent you to them. We inspect, photograph, write estimates, can meet the adjuster on site to point out what we documented, and provide documentation of the finished work. If you want someone to represent you in the claim itself, that is the role of a licensed public adjuster.
Will insurance pay for a new roof?
It depends on your policy and on what the adjuster finds, and no roofer can promise the answer. Policies are generally written for sudden damage, such as hail or wind, and not for normal wear or age. When storm damage is widespread, some insurers approve an insurance roof replacement; when it is limited, they may cover a repair. We document the damage accurately either way.
What does the insurance adjuster do?
The adjuster inspects the damage on behalf of the insurance company and reports what the policy covers. The adjuster does not work for you or for us. You can share our photos and estimate with the adjuster, and if you would like, we can be at the house during the inspection to point out the damage we documented so nothing is overlooked.
What if my shingles cannot be matched for a repair?
If your shingle line is no longer made in your color, a repair may leave a visible patch. We can send samples of your old shingles out for testing, and the report says whether a new shingle will match or not. You can present that report to your insurance company. How the insurer applies it depends on your policy, and we cannot promise how they will decide.
How long does a roof insurance claim take?
It varies with the insurer, the size of the damage and how quickly paperwork moves back and forth. Simple claims can move quickly, while larger or disputed claims can take months. If the roof is open to the weather while you wait, we can make temporary repairs to keep water out, and we will be ready to schedule the work once you have the insurer's decision.
Is storm damage to siding and gutters part of the same claim?
Often, yes, since one storm can damage the roof, siding, gutters and soffit at once. Whether each item is covered is up to your policy and adjuster. We inspect and photograph all of it, and we can repair siding, gutters, fascia and soffit along with the roof, so your documentation and the work stay in one place.
What should I do if my insurance company denied my roof claim?
Ask for the denial in writing with the reason, then set it beside the inspection report and photos we gave you. You can ask the insurer for a second adjuster, add weather records for the date of the storm, or hire a licensed public adjuster, who can negotiate for you in a way a roofer cannot. We keep supplying documentation through a dispute. If the claim stays denied, we give you a straightforward repair estimate, and financing is available upon credit approval.
What is matching coverage on a roof insurance claim?
It is the question of whether the insurer pays only for the damaged shingles or for enough of the roof to keep it looking uniform. Tennessee's insurance commissioner confirmed in 2017 that when replacement materials cannot match the rest in color, quality or size, the insurer should replace enough for a reasonably uniform appearance under the policy. A shingle sample report that shows no current match is the evidence that question turns on.
How do I meet with the adjuster on a roof insurance claim?
Schedule the adjuster's visit for a time one of our team can be on site. We walk the roof with the adjuster, point out what we documented and answer questions about the repair scope. You stay in the conversation, because we do not negotiate the claim for you.
Verify us
- Tennessee Department of Commerce and Insurance: Homeowners Insurance 101
- Tennessee Department of Commerce and Insurance: Consumer ResourcesVerify an insurance license or file an insurance complaint
- HAAGThe certification body behind our residential roof inspector credential
- Verify Tennessee contractor license 59116
Two offices
- Lebanon112 Tirzah Street, Lebanon, TN 37087(615) 455-3131
- Knoxville10440 Laurel Pointe Lane, Knoxville, TN 37931(865) 205-0800
Trusted like family.
Tell us what you are seeing. We will find the real problem.
Free estimates, photos of what we find, and a written proposal before any work starts. Open 24 hours, 7 days a week, with calls answered or returned day or night. On-site response depends on weather and safe working conditions.
Middle TennesseeLebanon office
(615) 455-3131East TennesseeKnoxville office
(865) 205-0800