Most people assume that storm damage to their roof, siding and gutters is covered by their homeowner’s insurance. And, to some extent, they’re probably right. However, you need to understand your specific policy and make sure you have the coverage you want for your home.
Perils
Your policy is either an all peril policy or a named peril policy. If you have the first, your storm damage will likely be covered to some extent. If you have a named peril policy, only damaged caused by those named perils will be covered. The perils covered by most policies include:
- Fire
- Lightening
- Wind
- Hail
- Snow/Ice
- Vandalism
Things not covered, also known as policy exclusions often include intentional acts, flooding and earthquakes. You can purchase separate flood and earthquake insurance if you live in an area prone to either or both.
Deductible
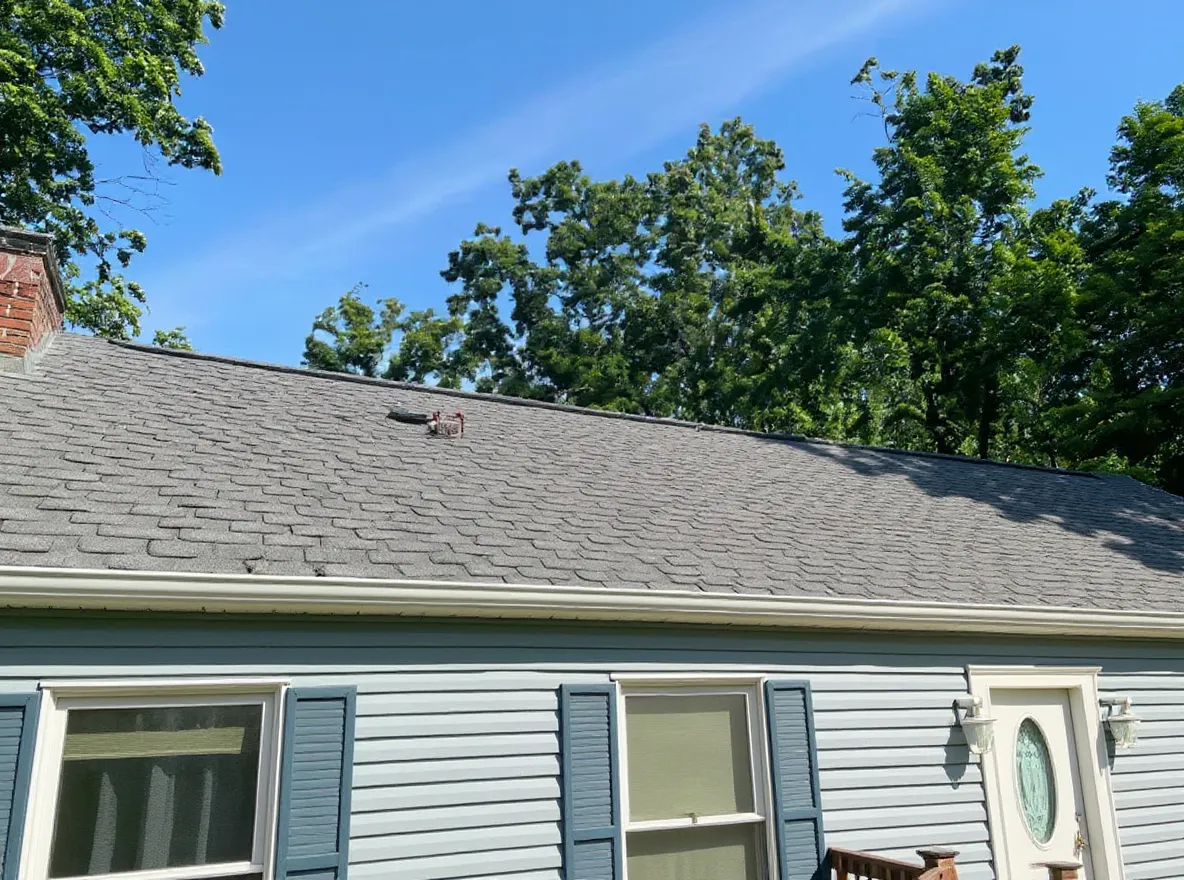
Virtually all insurance policies have a deductible. That is the amount you must pay before your insurance policy pays. Let’s say that your home has hail damage to your roofing, gutters and siding. Your adjustor sees the damage as a $30,000 claim. They’ll then look at your deductible, which usually ranged from $1,000 to $5,000 per claim, and payout only the balance. However, in addition to the deductible, you have a liability limit which is the maximum that they’ll pay out. Standard liability limit is $100,000.
The fine print
Although every policy is slightly different, there’s always the fine print you need to be aware of. One that often upsets homeowners after filing a storm damage insurance claim is when the adjustor informs you that they’re only paying out a percentage of the roof replacement. This often happens when the roof is older than 20 years. At that point it’s at the end of its life and the insurance company isn’t going to pay the full cost for a new roof when you likely needed one anyway. However, if your home sustained water damage, the repairs from the water damage should still be covered.
We’re storm damage insurance claims experts
If you have a storm damage insurance claim and need repair or replacement to your siding, gutters and roofing, call Mobley Brothers Roofing & Renovation. We accept all homeowner’s insurance claims and can help you with yours. One of our inspectors will meet with your adjustor if we don’t think you’re being treated fairly regarding your storm damage insurance claim. Call one of our Better Business Bureau A+ rated offices today for your appointment at (865) 205-0800 or (615) 455-3131.
Request a free estimate
A few details help us send the right person. If water is coming in right now, call instead.